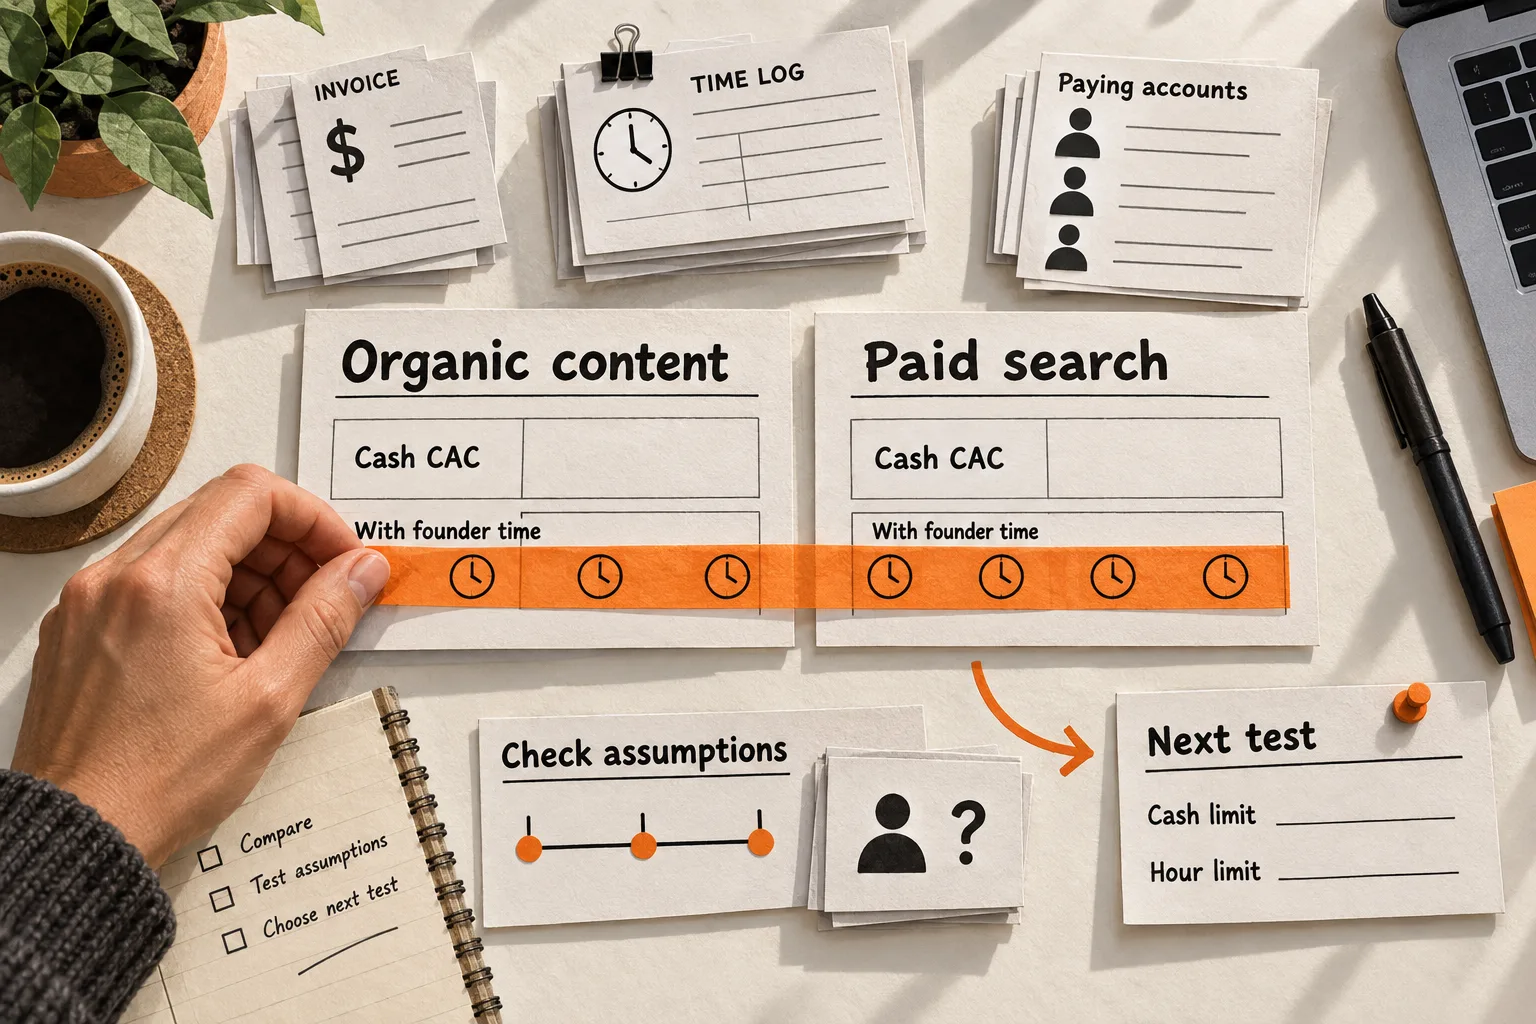
Compare acquisition channels using two numbers: cash customer acquisition cost (CAC) and CAC with founder labor included. Cash CAC helps you plan spending. The adjusted figure helps you decide where to put your working hours.
An organic channel can require little cash and still consume most of your week. Paid acquisition also takes founder time: setting up ads, reviewing creative, and following up with prospects. The worksheet below counts both on the same basis, then tests whether uncertain customer sources or a different hourly rate change the decision.
Calculate cash CAC and founder-adjusted CAC separately
The basic CAC formula divides sales and marketing acquisition costs by new customers acquired over a defined period. Relevant costs include salaries, tools, and acquisition spending. Paddle’s CAC guide
For this worksheet, use these definitions:
- Cash CAC = allocated acquisition cash costs ÷ new paying customers credited to the channel.
- Founder-adjusted CAC = (allocated acquisition cash costs − included founder acquisition compensation + assigned founder labor value) ÷ new paying customers credited to the channel.
Founder labor value is acquisition hours multiplied by your chosen hourly rate. Subtract only the founder compensation already included for that same work, channel, and period before adding the labor value. This counts the work once. If the founder is unpaid, the subtraction is zero.
HubSpot’s startup guide includes founder time as an acquisition cost and illustrates allocating the sales portion of a shared CRM bill. HubSpot’s startup CAC guide
The adjusted figure is a management estimate. Unpaid hours assigned a dollar value are not an additional cash payment. Label the two figures wherever you share them.
Set the customer definition and measurement window
Write one sentence defining a customer. For a subscription product, a workable starting point is: “One previously unpaid customer account that makes its first successful subscription payment.”
Count accounts consistently. Ten seats purchased by one company should not become ten customers in one channel and one customer in another. Keep trials, leads, renewals, and expansion purchases outside this denominator. Record refunds and early cancellations separately under a fixed policy so you can assess acquisition quality without silently changing historical counts.
A monthly reporting period is convenient, but it can pair this month’s spending with customers persuaded by work done much earlier. When that delay matters, maintain two views:
- A period view divides acquisition costs for a month or quarter by new paying customers during that period.
- A cohort view follows prospects first recorded during a specified period through a conversion cutoff, with acquisition costs allocated to that group.
For the cohort view, include spending on prospects who never convert and later follow-up work on the group. Otherwise, the numerator captures only successful selling. Record the cohort’s start and end dates, conversion cutoff, and open opportunities.
An unfinished cohort has a provisional CAC. If you cannot allocate costs reliably, use the period view and record the sales delay. Avoid comparing a mature cohort in one channel with an unfinished cohort in another as though both results were final.
Put a defensible value on founder hours
Choose a rate that answers your decision. For hiring or delegation, estimate what comparable work would cost to replace. To understand current compensation, divide actual compensation by working hours. Record which basis you chose and use it consistently across channels.
Use low, base, and high rate estimates to see whether the channel ranking changes. These are planning assumptions, not market benchmarks.
Track acquisition activities for a representative week or two: writing, distribution, prospect research, sales calls, follow-up, and campaign management. Mark reconstructed hours as estimates. A launch week may not represent ongoing effort, so explain how you estimated hours for the full reporting period.
Include founder labor on paid channels too. Ad setup, creative review, landing-page work, and sales follow-up all belong in the comparison.
Separate acquisition work from product development and service delivery. For an AI product, you might allocate prospect demo usage to acquisition while keeping model usage serving paying customers in delivery economics. Document how you split mixed activities.
If content consumes much of your week, the FindVex guide to setting a content repurposing budget can help you identify the work to include.
Reconcile costs and keep unknown customer sources visible
Assign direct ad spend to its channel. Split shared software, contractor work, and sales labor using a documented basis, such as recorded usage or acquisition hours. Keep the method stable enough to compare periods.
Separate setup effort from recurring work. For this worksheet’s cash view, retain the full acquisition-related payment in the period paid and flag large one-time costs. If you also spread an asset’s estimated economic cost across its useful life, keep that as a separate analysis with an explicit assumption. The founder-adjusted formula here changes labor valuation only.
Across channel records, costs should add up to the acquisition total, including any unallocated costs. Customer counts should add up to all new paying accounts, including those with unknown sources. Calculate blended CAC from those totals. A simple average of channel CACs gives each channel equal weight even when their customer counts differ.
Choose one rule for assigning customer credit. A manageable starting point is the first recorded acquisition source, with an “unknown” bucket. Connect each source record to a unique paying account and retain later touches separately. Under this rule, each account gets one channel assignment.
If you use Google Analytics attribution reports, record the model and lookback window. Google’s paid-and-organic last-click model gives credit to the last eligible channel and excludes direct visits unless the path consists entirely of direct visits. Its result can differ from a first-source worksheet. Google Analytics attribution documentation
When you ask customers how they found you, store their wording separately from your classification. A remembered recommendation and a tracked search visit can both describe parts of the same path.
Assigned credit does not establish how many purchases would disappear if you stopped a channel. Keep that limit attached to the comparison.
Worked example: compare organic content with paid search
Suppose an unpaid founder compares two channels over a quarter using the period view. Both target the same customer segment and count first-time paying accounts under the same attribution rule. All figures below are hypothetical.
Shared cash costs are already allocated. Founder hours include content or ad work plus sales follow-up. There is no founder compensation to subtract.
| Input or result | Organic content | Paid search |
|---|---|---|
| Acquisition cash costs | $300 | $1,500 |
| Founder acquisition hours | 45 | 10 |
| Credited paying customers | 6 | 5 |
| Cash CAC | $50 | $300 |
| Labor at $60/hour | $2,700 | $600 |
| Founder-adjusted CAC | $500 | $420 |
| Founder hours per customer | 7.5 | 2 |
Organic content’s adjusted CAC is ($300 + $2,700) ÷ 6 = $500 per customer. Paid search’s is ($1,500 + $600) ÷ 5 = $420.
Organic content requires less cash per customer. At the assumed hourly rate, paid search has the lower adjusted CAC and uses fewer founder hours per customer. Your available cash and time still constrain the choice.
Changing the hourly rate changes the ranking:
| Assumed hourly rate | Organic adjusted CAC | Paid adjusted CAC |
|---|---|---|
| $30 | $275 | $360 |
| $60 | $500 | $420 |
| $90 | $725 | $480 |
The two adjusted costs are equal at approximately $45.45 per hour. A decision based on the $60 estimate therefore depends on whether that rate is useful for the work you would delegate or give up.
Attribution can change the comparison too. Suppose two of the six organic customers have unresolved discovery histories. Crediting four customers to organic raises its adjusted CAC at $60/hour to $750. Keep the other two accounts in the unknown bucket, without assigning them to paid search or removing them from the overall count.
The totals still reconcile: four organic customers + five paid customers + two unknown customers = 11. With costs unchanged, blended cash CAC remains $1,800 ÷ 11, or about $163.64. Blended founder-adjusted CAC remains $5,100 ÷ 11, or about $463.64. Reclassifying a source changes the channel comparison, while total acquisition cost and total customers stay the same.
These small counts leave the ranking sensitive to individual customers. Use the comparison to choose another limited test before treating either channel as a durable winner.
Copy the channel worksheet and totals check
Create one record per channel and reporting period. Keep invoice, time-log, and customer-record references behind the totals. Use the same customer definition and cost rules throughout.
Channel:
Customer segment and offer:
Customer definition:
Refund and cancellation policy:
Reporting period:
View: period / cohort
If cohort: prospect entry dates and conversion cutoff:
Open opportunities and sales-delay notes:

Direct acquisition cash costs: $
Allocated shared acquisition cash costs: $
Allocation method:
One-time costs included:
Total acquisition cash costs (A): $
Founder acquisition compensation already in A (B): $
Founder acquisition hours (H):
Hours measured or estimated; estimation basis:
Hourly rate basis:
Low rate (R_low): $
Base rate (R_base): $
High rate (R_high): $

New paying accounts credited (N):
Customer-record references:
Attribution rule and lookback window:
Disputed assignments and alternative customer count:
Refunds and early cancellations:

Cash CAC = A / N
Adjusted CAC, low = (A - B + H × R_low) / N
Adjusted CAC, base = (A - B + H × R_base) / N
Adjusted CAC, high = (A - B + H × R_high) / N
Founder hours per customer = H / N
Adjusted CAC using alternative customer count:
Does the channel ranking change?

Main uncertainty:
Next change to test:
Cash limit: $
Founder hour limit:
Review date:
If no customers have converted, enter “No customers yet; CAC undefined” and retain the money and hours spent. Zero CAC would suggest free acquisition. The per-customer labor figure is also undefined when the customer count is zero.
Add this check across all channels, including unknown customer sources and unallocated costs:
Total acquisition cash costs (A_total): $
Total included founder acquisition compensation (B_total): $
Total assigned founder labor value at base rates (L_total): $
All new paying accounts (N_total):
Accounts assigned to named channels:
Accounts with unknown sources:

Do channel costs plus unallocated costs equal A_total?
Do named-channel accounts plus unknown accounts equal N_total?
Has each account been counted once?
Has each expense and block of founder time been counted once?

Blended cash CAC = A_total / N_total
Blended adjusted CAC = (A_total - B_total + L_total) / N_total
Include failed acquisition effort in the totals even when a channel has no customers. If the overall customer count is zero, both blended CAC figures are undefined.
Choose one change with a cash and time limit
Review CAC alongside early retention, service costs, and available cash. A low acquisition cost can bring customers who leave quickly or require expensive support. For AI products, inspect actual usage costs when judging what you can afford to spend acquiring an account.
Choose a change you can evaluate: reduce content production hours, improve a sales handoff, or run another paid test. Give it a cash limit, an hour limit, and a review date that allows prospects time to reach a purchase decision.
Start by completing the worksheet for two channels over one finished period. Reconcile the totals, calculate all three hourly-rate scenarios, and test one disputed customer assignment. If the ranking changes, write down which uncertainty you need to resolve before committing more of your week.